Can You Buy a Condo with a THB 15,000 Salary? How to Plan Your Mortgage Wisely
Buying a condominium is a long-term financial commitment that requires careful planning, especially for first-jobbers or working professionals earning around THB 15,000 per month who may be asking:
“Can I buy a condo with this salary?”
The answer is you can apply for a home loan, but approval is not guaranteed. Banks consider more than monthly income alone. They may also assess existing debt, income stability, repayment history, disposable income after essential expenses, and the price of the condominium you want to buy.
The more useful question is therefore not simply “How much can I borrow with a THB 15,000 salary?” but:
“What monthly mortgage payment can I comfortably afford while still maintaining enough money for daily expenses and emergency savings?”
For those looking for a condo in Bangna, a condo in Lasalle, a condo near BTS Bearing, or a condo near MEGABANGNA, REAL ASSET offers two ready-to-move-in projects with different lifestyle advantages: ARLO Sukhumvit 105 – Lasalle and A Space Mega 2.
Can You Buy a Condo with a THB 15,000 Monthly Salary?
A monthly salary of THB 15,000 does not automatically determine whether you can or cannot qualify for a mortgage.
Banks assess repayment capacity by looking at your income together with all existing financial obligations. They may also consider how much money remains after debt repayments and essential living expenses.
There is no single Debt Service Ratio, or DSR, percentage that can be universally applied to every borrower and every bank.
Therefore, using a fixed assumption such as “40% of a THB 15,000 salary equals a THB 6,000 monthly mortgage payment” is not an accurate way to predict approval.
Factors that may be considered include:
Regular and verifiable income
Credit card obligations
Personal loans
Car loan repayments
Other recurring debt
Repayment history
Savings and emergency funds
Condominium price and requested loan amount
3 Questions to Ask Yourself Before Buying a Condo
Before applying for a mortgage, start with three practical questions.
1. How much money is left after essential expenses?
Do not calculate affordability from your full salary. Consider food, transportation, insurance, phone bills, family expenses, and existing debt first.
2. Will you still have savings after adding a mortgage payment?
Condo ownership involves more than monthly mortgage instalments. Other expenses may include common area fees, utilities, insurance, furnishing, maintenance, and unexpected costs.
3. Could you continue making payments if your income temporarily decreased?
Maintaining an emergency fund can help reduce financial pressure, especially during the early years of a mortgage.
5 Important Things to Consider Before Applying for a Condo Loan
1. Do Not Look Only at the First-Year Interest Rate
Home loans may use different interest structures, such as fixed rates for a certain period or rates that change over time according to the loan package.
Instead of comparing only the first-year rate, review:
Interest rates throughout the promotional period
Rates after the promotional period
Monthly repayments
Loan term
Fees
Mortgage insurance conditions, if applicable
Early repayment conditions
Comparing offers from several banks can provide a clearer picture of the total borrowing cost.
2. Refinancing Does Not Always Have to Happen After Exactly 3 Years
Refinancing means moving your mortgage to another bank to obtain different loan conditions or potentially lower borrowing costs.
However, the appropriate timing depends on the terms of your existing mortgage agreement. A contract may include conditions lasting 3 years, 5 years, or another period.
Before refinancing, compare the interest savings against possible expenses such as:
Property appraisal fees
Mortgage registration fees
Stamp duty
Other administrative costs
Early repayment charges, if applicable
The decision should be based on the net financial benefit, not the new interest rate alone.
3. Retention Is Another Option Before Changing Banks
Retention refers to negotiating a new rate or revised conditions with your existing bank.
One advantage is that you may not need to move your mortgage to a new lender, and the process may involve fewer steps or lower costs than refinancing.
However, retention is not automatically better or worse than refinancing.
Compare the existing bank’s offer with alternatives from other lenders, including interest costs, fees, and conditions over the period you plan to keep the loan.
4. Prepare for Expenses Beyond the Down Payment
Even if a bank approves a relatively high loan amount, buyers should maintain savings for other costs, including:
Any difference between the purchase price and approved financing
Ownership transfer expenses
Mortgage registration fees
Furniture and appliances
Common area fees
Emergency savings
Using all available cash on the transfer date can create unnecessary financial pressure after moving in.
5. Choose a Condo Based on Your Real Lifestyle, Not the Maximum Loan Amount
A bank approving a certain amount does not mean you need to borrow the full amount.
If you commute by public transport every day, living close to a BTS or MRT connection may help reduce travel time and transportation expenses.
If you primarily drive and work around Bangna–Suvarnabhumi, a condominium with convenient access to major roads, expressways, and lifestyle destinations may be more suitable.
What Documents Are Commonly Required for a Condo Mortgage?
Exact requirements vary by bank, occupation, and income structure, but documents can generally be grouped into three categories.
Personal Documents
National ID card
House registration
Name-change documents, if applicable
Marriage-related documents, where relevant
Income Documents
Salaried employees
Banks may request salary slips, an employment certificate, and bank statements for a period specified by the lender.
Business owners
Documents may include bank statements, company registration documents, commercial registration, tax documents, financial statements, and other proof of income.
Self-employed applicants
Banks may ask for bank statements, proof of income, withholding tax documents, or other evidence showing the source of earnings.
Property Documents
These may include a reservation document, sale and purchase agreement, and other project documents required by the lender.
Because the required statement period and supporting documents can vary, it is best to request an official checklist directly from the bank before applying.
What Should First-Time Condo Buyers Consider?
For people earning around THB 15,000 or just beginning to build their financial foundation, choosing a condominium should involve more than the selling price.
Consider:
Monthly transportation costs
Common area fees
Daily commuting expenses
Unit size
Facilities you will genuinely use
Your preferred transportation mode
Surrounding environment
Ready-to-move-in status
Long-term ownership costs
If you have a pet, also check whether the condominium permits pets, as this directly affects everyday living.
ARLO Sukhumvit 105 – Lasalle: A Ready-to-Move-In Pet-Friendly Condo Near BTS Bearing
ARLO Sukhumvit 105 – Lasalle is a ready-to-move-in condominium in the Sukhumvit 105–Lasalle area, suitable for working professionals who want to live around Sukhumvit–Bangna with access to mass transit.
The project is a Low Rise condominium with 8 storeys across 4 buildings and 581 units.
Available unit types include:
1 Bedroom: 25 sq.m.
1 Bedroom: 30 sq.m.
1 Bedroom Plus: 34.5 sq.m.
2 Bedroom: 44 sq.m.
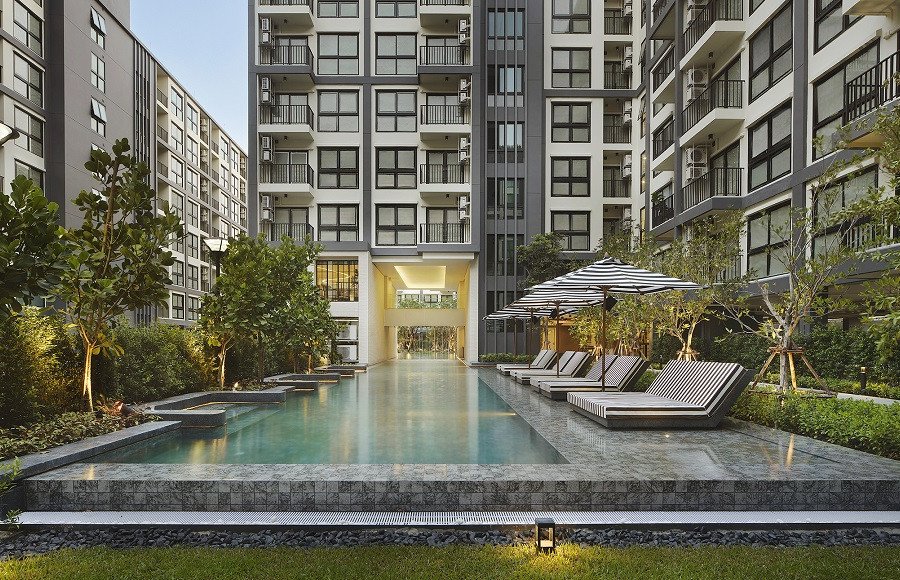
One of the project’s key features is its Pet-Friendly concept, with dedicated pet areas such as Pet Corner / The Pet Courtyard for residents who want to live with their pets.
Facilities include a 50-metre Lap Pool, Fitness, Co-Working Space, Reading Garden, Star View Rooftop, and additional relaxation areas.
The Sukhumvit 105 location connects to BTS Bearing and the MRT Yellow Line, while REAL ASSET states that the project is approximately 5 minutes from BTS Bearing*.
The surrounding area also includes Lasalle’s Avenue, Dadfa Lasalle 33, BITEC, international schools, and hospitals.
The current starting price shown by REAL ASSET is approximately THB 1.89 million*. Prices, promotions, and available units should be confirmed again at the time of purchase.
A Space Mega 2: A Bangna Condo Next to MEGABANGNA and IKEA Bangna
A Space Mega 2 is a 34-storey High Rise condominium with 998 units, located within Mega City Bangna on Bangna-Trad Road.
Its location next to MEGABANGNA and IKEA Bangna provides convenient access to restaurants, supermarkets, shopping, entertainment, and everyday services.
The project offers several unit types, including:
1 Bedroom: approximately 28.52 sq.m.
1 Bedroom Plus: 31.06 sq.m.
1 Bedroom: approximately 34.97 sq.m.
2 Bedroom: approximately 56.32 sq.m.
2 Bedroom: approximately 62.42 sq.m.
Another highlight is the Mega Sky Facilities, including:
Sky Infinity Edge Pool
Sky Jogging Track
Sky Park
Full Function Fitness
Co-Living Space
Co-Kitchen Space
Meeting Room
The location connects conveniently to Bangna-Trad Road, Kanchanaphisek Road, and expressways.
REAL ASSET states that A Space Mega 2 is approximately 10 minutes from Suvarnabhumi Airport*.
The current starting price shown by REAL ASSET is approximately THB 1.89 million*. Buyers should confirm current promotions and available units before making a decision.
ARLO Sukhumvit 105 – Lasalle vs. A Space Mega 2: Which One Fits Your Lifestyle?
From a lifestyle perspective, ARLO Sukhumvit 105 – Lasalle may be suitable for those who:
Work around Sukhumvit, Bangna, or along mass-transit routes
Prefer a Low Rise condominium
Want a Pet-Friendly residence
Need access to BTS and the MRT Yellow Line
Enjoy the Lasalle–Sukhumvit lifestyle
Meanwhile, A Space Mega 2 may suit those who:
Live or work around Bangna–Suvarnabhumi
Want to be next to MEGABANGNA and IKEA Bangna
Mainly travel by car and use expressways
Prefer extensive shared facilities and elevated common areas
Want unit options ranging from 1 Bedroom to 2 Bedroom
Neither project is automatically “better” for everyone. The right choice depends on your commuting pattern, monthly expenses, and everyday lifestyle.
What Condo Price Can Someone Earning THB 15,000 Afford?
There is no universal answer.
Someone earning THB 15,000 with no existing debt may be assessed differently from someone earning the same amount while paying a car loan or carrying credit card debt.
If you are considering a condo with a starting price of around THB 1.89 million*, such as ARLO Sukhumvit 105 – Lasalle or A Space Mega 2, it is advisable to request a preliminary loan assessment from a bank before making a reservation.
This can help you understand:
How much down payment or additional cash may be required
The estimated monthly instalment
Whether a co-borrower may be necessary
Whether your current income and debt profile can support the requested loan
A THB 15,000 salary does not automatically mean you can borrow enough for a THB 1.89 million condominium.
Refinancing or Retention: Which Is Better?
There is no single answer.
If your existing lender offers a competitive retention package with limited costs, moving to another bank may not be necessary.
However, if a new lender offers significantly lower total borrowing costs after all refinancing expenses are included, refinancing may be worthwhile.
Before deciding, compare:
Interest costs over the period you plan to keep the loan
New monthly payments
Processing and registration costs
Early repayment conditions
Any benefits or incentives that may need to be repaid to the existing lender
Buying a Condo Within Your Means Matters More Than Borrowing the Maximum
For someone earning around THB 15,000 per month, condo affordability cannot be determined by salary alone.
Existing debt, disposable income, savings, income stability, and ongoing ownership costs all need to be considered together.
If you are looking for a condo in Bangna, you can compare ARLO Sukhumvit 105 – Lasalle, which focuses on mass-transit connectivity and Pet-Friendly living, with A Space Mega 2, which emphasizes its location next to MEGABANGNA and access to the Bangna–Suvarnabhumi area.
Before making a reservation, check the latest price, promotion, available units, and request a preliminary mortgage assessment from a bank so that your decision is based on your actual financial position.
Mortgage approval, approved loan amounts, interest rates, repayment terms, and other conditions remain subject to each bank’s lending criteria.
------------------------------------------
Website : www.realasset.co.th
Facebook : www.facebook.com/RealAssetDevelopment
Instagram : www.instagram.com/realasset.development/
LINE Official : @realasset หรือ https://lin.ee/kSfFgQP
Youtube : www.youtube.com/@RealAssetProperty
Call Center : 1232
E-Mail : info@realasset.co.th
Frequently Asked Questions About Buying a Condo with a THB 15,000 Salary
Q: Can I get a condo mortgage with a THB 15,000 monthly salary?
A: You can apply, but approval depends on your income, existing debt, repayment history, disposable income, and the lender’s criteria. Salary alone cannot determine the approved loan amount.
Q: How much can someone earning THB 15,000 afford to pay for a condo each month?
A: There is no single amount that applies to everyone. Banks assess total debt obligations and the amount of income remaining for daily living, so an individual assessment is more reliable than using a fixed percentage.
Q: Do I need a down payment before buying a condominium?
A: It depends on the approved loan amount, property valuation, lending criteria, and applicable conditions at the time. Buyers should still prepare funds for any financing shortfall and other related expenses.
Q: Can someone earning THB 15,000 get a loan for a THB 1.89 million condo?
A: This cannot be determined from salary and property price alone. The bank must assess the applicant’s debt, income, credit profile, and repayment capacity first.
Q: Who is ARLO Sukhumvit 105 – Lasalle suitable for?
A: It is suitable for those looking for a ready-to-move-in condominium in the Lasalle–Bangna area, with access to BTS Bearing and the MRT Yellow Line, as well as residents who want a Pet-Friendly condominium.
Q: Who is A Space Mega 2 suitable for?
A: It is suitable for buyers looking for a Bangna condominium next to MEGABANGNA and IKEA Bangna, with convenient access to expressways and Suvarnabhumi Airport, together with a wide range of shared facilities.
Q: Do I have to wait exactly 3 years before refinancing a condo mortgage?
A: Not necessarily. The appropriate timing depends on the conditions in your existing mortgage agreement, which may specify 3 years, 5 years, or another period.
Q: What is the difference between retention and refinancing?
A: Retention means negotiating revised loan conditions with your existing bank, while refinancing means moving the mortgage to another lender. Compare interest costs, fees, and the overall financial benefit before choosing either option.